A personal loan from Mizuho Bank in Spain sounds straightforward enough. Search the phrase and dozens of guides tell you about eligibility, rates, and application steps.
The bank's Madrid branch operates under Mizuho Bank Europe N.V. and handles corporate banking only. Mizuho's own global site carries a warning about scam communications pretending to offer consumer services outside Japan.
This guide is built for expats and legal residents in Spain comparing lenders, especially those drawn to international banks over domestic ones.
Mizuho's Madrid Branch and What It Does
A lot of personal loan guides treat Mizuho Bank in Spain like a retail lender. That framing misses the structure of how the bank operates in Europe.
Mizuho Bank Europe N.V. is incorporated in the Netherlands, supervised by De Nederlandsche Bank. The Madrid office is a branch of that Dutch entity, registered under Spain's national bank code 1559 with the Banco de España.
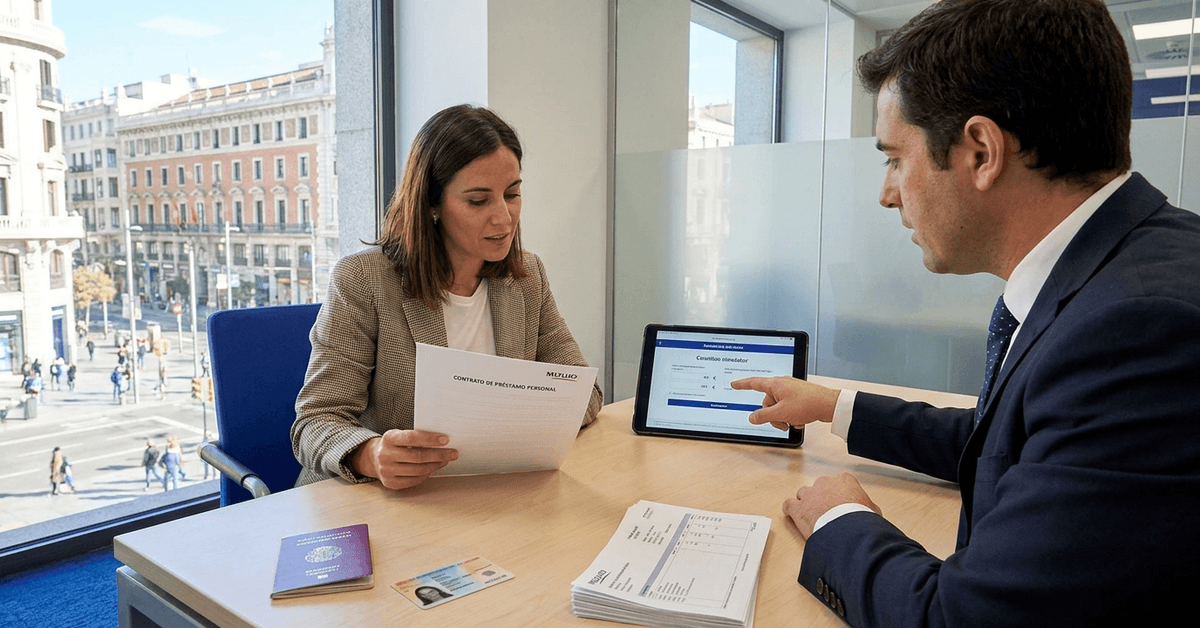
The branch employs a small team and focuses on corporate finance, syndicated loans, and project finance for institutional clients.
Mizuho's EMEA Warning About Consumer Services
The Mizuho Bank global site carries a direct statement about this. The bank says it does not provide retail investor services in the EMEA region or anywhere outside Japan.
That warning exists because of social engineering scams where individuals pose as Mizuho representatives to target consumers. I think the confusion around Mizuho personal loans in Spain comes from aggregator sites that list every bank with a Spanish branch as a potential lender.
Mizuho has over 100 offices outside Japan, but every single one handles corporate and investment banking. The retail arm operates only in Japan, with over 505 domestic branches.
Why International Bank Searches Can Mislead
I would push back against the common advice to seek out international banks for personal loans in Spain. The assumption is that a global name equals better terms or more flexibility.
But the cheapest personal loan rates in Spain right now, August 2026, come from domestic online lenders and fintech platforms. Bankintercard starts at 4.54% TAE. ING's Préstamo Naranja sits at 5.49% TIN. BBVA charges 5.6% TIN for its quick online loan.
A Japanese megabank with €1.9 trillion in global assets does not make it a competitor in Spanish consumer lending. Size and reputation in corporate finance have zero transfer to personal loan pricing.
How Personal Loans Work in Spain in 2026
The Spanish lending market has two interest rate figures that confuse almost everyone who didn't grow up with them. Getting this wrong changes what a loan costs by hundreds of euros.
TIN vs. TAE: The Only Numbers That Matter
A loan with a 4.45% TIN might carry a 5.75% TAE once fees get added. That gap is the real cost of the loan, and it varies wildly between lenders.
- TIN (Tipo de Interés Nominal) is the raw percentage the bank charges on your outstanding balance. It excludes fees, commissions, and timing of payments.
- TAE (Tasa Anual Equivalente) folds in the TIN plus opening commissions, administrative fees, and repayment frequency. TAE is the number for comparing offers.
The current best personal loan TAE in Spain starts around 4.54% from Bankintercard's consumer finance arm, and competitive rates from Santander begin at 5.24% TIN.
Typical Loan Amounts and Repayment Periods
Spanish personal loans follow a general range across lenders:
- Amounts from €1,000 to €75,000 depending on the lender (Cetelem, under BNP Paribas, goes up to €75,000)
- Repayment terms between 12 and 60 months for most online lenders, though some banks offer up to 8 years
- Opening commissions range from 0% (online lenders like Bankintercard) to 2% or more at traditional banks
That commission difference on a €20,000 loan can mean €400 extra paid before a single interest charge hits. Checking whether a lender charges an opening fee (comisión de apertura) should happen before comparing TIN or TAE.
Spain's Credit Check System: ASNEF and CIRBE
If you're used to FICO scores or credit ratings from the US or UK, Spain's system will feel unfamiliar. There is no numerical credit score for individuals.
What ASNEF and CIRBE Track
If your name does not appear on ASNEF and your CIRBE report is clean, you start from a neutral position.
A 20-year history of perfect payments in Germany or Japan gives you zero advantage over someone who has never borrowed a euro. Every applicant without a negative listing begins at the same point.
- CIRBE (Central de Información de Riesgos del Banco de España) is managed by Spain's central bank. It records all outstanding loans above €6,000 from any financial institution.
- ASNEF is run by Equifax Spain and records defaults only. Same for BADEXCUG, run by Experian Spain. Neither tracks on-time payments. Neither assigns a score.
How to Check Before Applying
Multiple loan applications in a short window generate multiple CIRBE queries, and Spanish lenders interpret that pattern as financial distress. Spacing applications out matters more than most guides mention.
- Check your CIRBE report for free through the Banco de España's portal at clientebancario.bde.es
- Request your ASNEF data through Equifax Spain's access portal
- Review BADEXCUG records through Experian Spain
- Resolve any disputed entries before submitting a single loan application
An unpaid telecom bill from three years ago can land you on ASNEF and block a €30,000 loan approval. The bill might be €47.
That mismatch between the size of the debt and the size of the consequence is something I was surprised to find when checking Expatica's credit guide for Spain.
Comparing Real Lenders for Personal Loans in Spain
Since Mizuho is off the table for consumer lending, the practical comparison involves banks and fintech lenders that serve individuals.
| Lender | TAE (from) | Max Amount | Opening Fee | Process |
|---|---|---|---|---|
| Bankintercard | 4.54% | Varies | 0% online | 100% online |
| Cofidis | 5.99% | €30,000 | 0% | Minutes response |
| ING (Préstamo Naranja) | 5.63% | €40,000 | 0% | Online, existing clients |
| BBVA | 5.75% | €75,000 | Varies | Online, no documents option |
| Cetelem (BNP Paribas) | Competitive | €75,000 | Varies | 100% online |
The cheapest rate on paper may not be the cheapest rate for your profile. TAE figures listed as "from" (desde) represent the lowest offered to top-tier credit profiles.
The same lender might quote 13.69% TAE to a different applicant based on amount, term, and creditworthiness.
What Disqualifies an Application
Lenders run ASNEF and CIRBE checks as standard procedure. Beyond those, common disqualifiers include:
- Debt-to-income ratio above 35% of net monthly income (all debts combined, including the new loan)
- Irregular income patterns visible in bank statements
- Gambling transactions flagged in the last 6 months of statements
- Employment contracts shorter than the loan repayment term
- Applications submitted to multiple lenders within weeks of each other
That last point catches people off guard. Applying to four banks in one week to "compare offers" can trigger a CIRBE flag that makes the fifth application harder, not easier.
Questions People Ask About Mizuho Bank Personal Loans in Spain
These are the questions that come up most around this topic, with answers that fill in gaps from the sections above.
- Q: Does Mizuho Bank offer personal loans to individuals in Spain?
No. Mizuho's Madrid branch handles corporate and investment banking only. The bank's global site explicitly states it does not provide retail services in the EMEA region. Any communication offering Mizuho consumer loans outside Japan should be treated with caution. - Q: Can I get a personal loan in Spain as a foreigner or expat?
Legal residents with a NIE (Número de Identidad de Extranjero) and stable income can apply at most Spanish lenders. The challenge is building a local credit footprint, since on-time payments outside Spain do not transfer to CIRBE or ASNEF records. - Q: What is the cheapest personal loan available in Spain in 2026?
Bankintercard currently offers the lowest starting TAE at 4.54%. Cofidis follows at 5.99% TAE with fast online approval. Both require no bank-switching, and neither charges an opening commission on online applications.
Conclusion
Mizuho Bank is a major global institution, but its Spain presence does not extend to personal lending for individuals. Knowing that gap saves time that would otherwise go toward an application that cannot exist.
The Spanish personal loan market has competitive options from domestic lenders, and the TAE comparison is where the real savings sit.
Checking ASNEF and CIRBE before applying to even one lender is the single step most likely to prevent a surprise rejection.