Fast loans in Kenya can land in your M-Pesa within two minutes of tapping "accept." The speed is the whole pitch, and it is also why so many borrowers confirm terms they never read.
The repayment summary appears on your screen before you confirm. Most expensive surprises in digital lending sit on that single screen, tucked under "other fees" and late penalties.
This guide is for the first-time borrower with a Safaricom line and an urgent bill. You want cash today, and you also want your credit record intact when you need a bigger loan next year.
How Do You Apply for a Fast Loan in Kenya Today?
You download a licensed lender's app, register with your Kenyan ID, pick an amount and repayment period, then accept the terms. The money goes straight to your M-Pesa wallet.
A fast loan in Kenya is a short-term personal loan processed through a mobile app or website and usually paid out to M-Pesa. Apps accept applications 24/7, with no branch visit and no stack of paperwork.
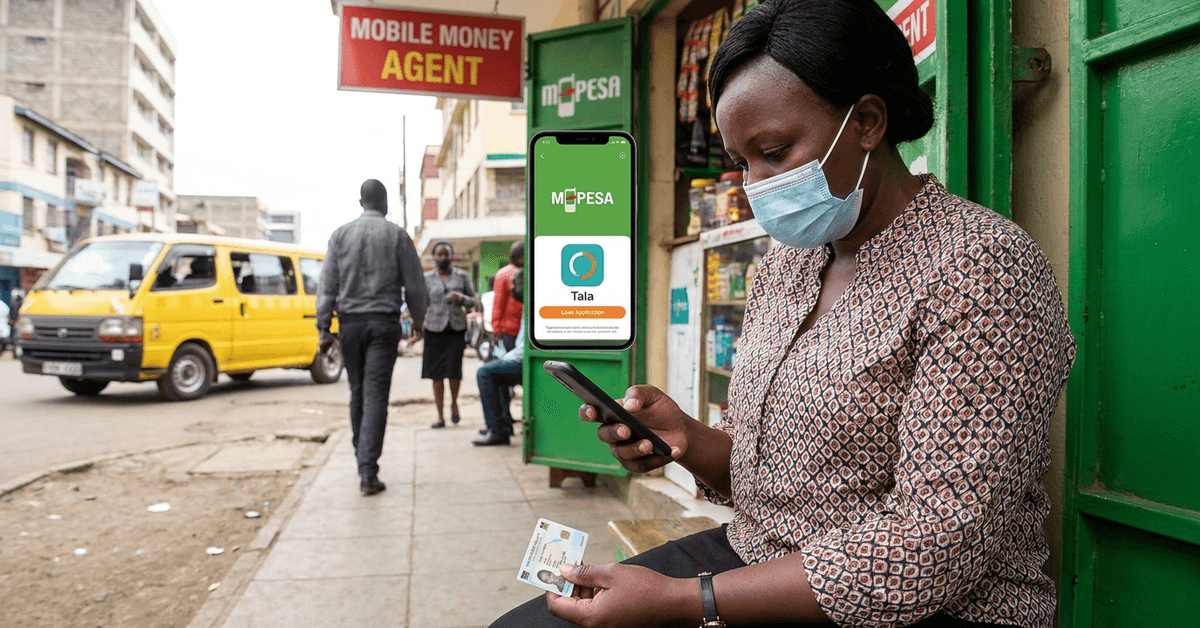
What You Need to Qualify
Lenders ask for a valid Kenyan ID, Kenyan citizenship, and an age of at least 18. Some lenders set a higher minimum age depending on their own risk rules.
An active Safaricom line is usually required, since funds and repayments move through M-Pesa. Lenders may also review your M-Pesa or bank statements for salary deposits or business income.
How Long Approval Takes
New accounts are often verified within an hour, sometimes faster. Once you apply, an automatic assessment runs, and approval can show up instantly.
After you accept, the cash can arrive in your wallet in about two minutes. So yes, you can borrow money faster than you can boil water for chai.
Why Your M-Pesa History Decides the Loan Before You Apply
The form takes minutes, but the decision leans on records you built over the previous months. Fast loan apps assess applicants using automated checks on profile details, credit history, and transaction records like M-Pesa statements.
So the real application starts long before you open the app. Regular credits, such as salary deposits or steady business income, give the system something to approve.
What This Means for Your Timing
If you run a small business, keep income flowing through the same line you plan to borrow with. Splitting money across several numbers leaves each one looking thinner.
Think of every past repayment as a reference letter you wrote for yourself. A clean record now makes the next emergency cheaper to handle.
Which Fast Loan Apps in Kenya Can You Trust?
Start with lenders licensed by the Central Bank of Kenya, then compare terms. The Central Bank of Kenya publishes a list of licensed digital credit providers on its official website.
Plenty of advice tells you to read user reviews and forum threads first. I'd put the Central Bank of Kenya licensed lenders list ahead of any review, because a five-star rating proves nothing about licensing, and only licensing gives you a formal dispute route.
Popular Licensed-Style Apps to Compare
These three names come up most often for quick cash:
- Tala: an early mobile lender in Kenya, using smartphone data and basic ID details to make offers.
- Branch: an app-based lender offering personal loans with flexible terms and instant funding options.
- Zenka: a digital lender where new users may get a discounted interest rate on their first loan, subject to approval.
Check each one against the CBK list yourself before signing up, since licensing status can change. You can see Tala's current terms on the official Tala Kenya site.
Who These Apps May Suit
Mobile loans can be suitable for small, one-off gaps you can repay within weeks. They fit poorly when the shortfall comes back every month.
What Do Fast Loans in Kenya Really Cost?
The true cost is the interest plus every listed fee plus any late penalty. Administrative charges and late penalties in digital lending can be high, so the headline rate tells only part of the story.
Read the summary screen line by line before you confirm. Look for these items:
- The total repayment amount, written as one number
- Any "other fees" or processing charges added to the loan
- The exact due date and what happens one day after it
- The late penalty amount or rate
If the app hides any of these, close it. A lender that blurs the total before you sign rarely gets clearer after.
Borrow the Minimum
Asking for more than you need raises your repayment strain without solving anything extra. Work out the exact bill amount first, then request that figure.
What Happens to Your Credit Record After a Fast Loan?
Every fast loan leaves a trail. Every fast loan application, approval, or late payment can be recorded at Kenya's credit bureaus.
Good repayment history can help you secure better rates later. Missed payments can make future borrowing harder or pricier.
The Late Payment Trap
Late repayment can bring collection efforts and higher rates on your next loan. Set a phone reminder a few days before the due date, or automate the payment if your lender allows it.
The Unlicensed Lender Trap
Fraud still happens in Kenyan digital lending. An unlicensed app can cost you both money and personal data, including your ID photos and contacts.
A few warning signs deserve a hard stop:
- The app is missing from the CBK licensed list
- It asks for an upfront payment before releasing the loan
- The fees appear only after you have accepted
Are There Cheaper Alternatives to Fast Loans in Kenya?
Yes, and some are worth asking about first if you have a few days. Chamas and SACCOs often lend at lower interest with longer repayment periods than mobile apps.
The options compare like this:
| Option | Speed | Typical Cost | Repayment Period |
|---|---|---|---|
| Fast loan app | Minutes | Higher, with fees and penalties | Weeks to months |
| Chama or SACCO loan | Slower, needs membership | Often lower interest | Longer terms |
| Employer salary advance | Depends on workplace | May be lower cost | Set by employer policy |
| Personal savings | Immediate | No interest | None |
Speed costs money, so pay for it only when the bill cannot wait.
Salary Advances and Savings
Some employers allow salary advances, though limits and rules vary by workplace. Ask HR about the policy before an emergency, so you know the answer when it matters.
An emergency fund in a savings account or mobile wallet is the lowest-risk backup. It grows slowly, and that is fine.
Questions People Ask About Fast Loans in Kenya
These come up often from first-time borrowers, so the short answers sit below.
- Q: Can I get a fast loan in Kenya without a payslip?
Many apps look at your M-Pesa transaction history instead of a formal payslip. Steady business income passing through your line can work in your favour. - Q: Do I need a Safaricom line for mobile loans?
Most fast loan providers pay out and collect through M-Pesa, so an active Safaricom line is generally required. Check the specific app's terms if you use another network. - Q: Will checking several loan apps hurt my credit?
Applications and approvals can be recorded at credit bureaus. Compare terms on the summary screens first, then apply only where you plan to borrow. - Q: How do I know if a loan app is a scam?
Search for the lender on the Central Bank of Kenya's licensed list. Walk away from any app demanding money before it releases yours. - Q: Is it safe to take a second loan to repay the first one?
That pattern usually signals a monthly shortfall, which mobile loans handle poorly. A SACCO loan or salary advance may suit that gap better.
Conclusion
Fast loans in Kenya can rescue a tight week when you read the full repayment summary first. Check the Central Bank of Kenya list before installing any app, however good its reviews look.
Borrow the exact bill amount, repay before the due date, and your credit record keeps working for you. Your next emergency loan could be cheaper, so treat today's repayment as preparation for that one.